
Quick answer: Investment risk is the possibility that an investment will lose value, produce a lower return than expected, or fail to meet the goal you were investing for. Every investment involves some form of risk. The useful question for a beginner is not whether risk can be eliminated, but whether the risks of an investment are understood and appropriate for the purpose of the money.
Risk can come from many sources. The market can fall, an individual company can perform badly, interest rates can change, inflation can reduce purchasing power, an investment can become difficult to sell, and fees or taxes can reduce the amount you keep. Some risks are visible in a price chart; others are much easier to overlook.
This guide explains the main types of investment risk beginners should understand, how different risks interact, and what questions to ask before putting money into an investment.
What Is Investment Risk?
Investment risk is the uncertainty surrounding the future value or return of an investment.
If you buy an investment for £1,000, you might later have more than £1,000, less than £1,000, or roughly the same amount. The outcome depends on the investment and the conditions affecting it.
Risk therefore has two dimensions:
- What could go wrong? This identifies the source of the risk.
- How would it affect your goal? This identifies the practical consequence.
For example, a share price falling 20% is a market risk. Whether that fall is a temporary fluctuation or a serious problem depends partly on when you need the money and whether you can tolerate the loss.
Risk Is Not the Same as Losing Money
A useful distinction is between risk and an actual loss.
Risk is the possibility of an unfavourable outcome. A loss occurs when the investment actually falls in value or is sold for less than the amount invested.
Investments with higher potential returns often involve greater uncertainty, but a higher level of risk does not guarantee a higher return. There is no reliable rule that says taking more risk will always make you more money.
The Financial Conduct Authority’s InvestSmart guidance encourages investors to understand the risks involved and consider whether an investment is suitable for their circumstances.
Source: FCA InvestSmart.
1. Market Risk
Market risk is the possibility that the overall market or a broad group of investments will decline.
Share markets can fall because of changing economic conditions, company earnings, interest rates, investor expectations, geopolitical events and many other factors.
Market risk cannot be completely removed from a portfolio of market-based investments. Even a broadly diversified portfolio can fall when markets decline together.
For a long-term investor, a temporary market fall may be manageable if the money is not needed immediately. For someone who needs the money soon, the same fall can create a much more serious problem.
This is why time horizon matters. Tinywealth’s investment time horizon guide explains how the timing of a financial goal can affect how market volatility should be considered.
2. Company or Business Risk
If you own shares in an individual company, you are exposed to risks specific to that business.
A company could lose customers, face stronger competition, experience management problems, carry too much debt, suffer a product failure, or operate in an industry that changes quickly.
In extreme cases, a company can fail and shareholders can lose most or all of their investment.
This is one reason diversification matters. Owning investments across different companies can reduce dependence on the outcome of any single business, although diversification cannot prevent all losses.
See Tinywealth’s guide to diversifying a small investment portfolio for a practical introduction.
3. Concentration Risk
Concentration risk occurs when too much of a portfolio depends on one investment, company, sector, country, theme or other narrow exposure.
Imagine two investors who each have £5,000.
Investor A has most of the money in one company. Investor B spreads the money across many companies and sectors.
If that one company experiences a major problem, Investor A may be affected much more severely. Investor B may still experience losses, but the impact of one company may be smaller.
Concentration can also be hidden. Several different funds may own many of the same large companies, meaning an investor may have more exposure to those companies than expected.
4. Interest Rate Risk
Interest rate risk is particularly relevant to bonds and other interest-sensitive investments.
When market interest rates change, the value of existing bonds can move. The relationship is not identical for every bond, but generally, existing fixed-rate bonds can fall in market value when comparable new bonds offer higher interest rates.
Interest rates can also affect shares and property through borrowing costs, economic conditions and investor expectations.
The important lesson is that interest rate risk is not limited to a bank savings account. Different financial assets can respond to changing rates in different ways.
5. Inflation Risk
Inflation risk is the possibility that the purchasing power of your money will decline over time.
Suppose you keep £1,000 for several years. The number on your account may remain £1,000, but if prices rise during that period, the money may buy fewer goods and services than it did originally.
This creates an important distinction:
- Nominal value: the amount of money you have.
- Real value: what that money can actually buy.
Cash can therefore have very low price volatility while still carrying a long-term purchasing-power risk.
6. Liquidity Risk
Liquidity refers to how easily an investment can be converted into cash without a significant effect on its price.
Some investments can generally be bought or sold relatively easily. Others may take longer to sell or may involve a wider difference between the price at which you can buy and sell.
Liquidity becomes especially important when you have a short time horizon or an unexpected need for cash.
An investment that is difficult to sell at the time you need money can create a practical problem even if the investment itself has performed well over a longer period.
7. Credit or Default Risk
Credit risk is the possibility that a borrower will fail to make payments as expected.
This can matter when you invest in bonds or other debt instruments. Governments and companies borrow money from investors, but the ability to repay can differ between issuers.
A bond is therefore not simply “safe” because it pays interest. Investors should consider who issued it, what obligations exist, and what could happen if the borrower experiences financial difficulty.
8. Currency Risk
If you invest in assets denominated in a foreign currency, changes in exchange rates can affect the value of your investment when measured in pounds.
For example, a foreign investment could rise in its local currency while the pound also strengthens against that currency. The return measured in pounds could therefore be smaller than the local-market return.
Currency exposure can be useful for diversification, but it introduces another source of uncertainty that investors should understand.
9. Sequence-of-Returns Risk
Sequence-of-returns risk is particularly important when an investor is withdrawing money from a portfolio.
Two portfolios can experience the same average returns over a period but produce different outcomes if the order of good and bad returns is different.
This matters because withdrawals reduce the amount of money remaining to participate in future market recoveries.
The concept is therefore particularly relevant to people approaching or living in retirement, although the general principle is useful for anyone taking money out of an investment portfolio.
10. Reinvestment Risk
Reinvestment risk is the possibility that income or returned capital cannot be reinvested at the same rate that was previously available.
For example, an investor may receive interest from a bond or savings product and later discover that comparable opportunities offer lower rates.
The investment may have performed as expected, but the investor’s future income or growth opportunity can still change because the available reinvestment rate has changed.
11. Fees and Cost Risk
Fees are not normally described as market risk, but they can materially affect investment outcomes.
Possible costs include:
- Platform or account fees.
- Fund management charges.
- Trading or dealing costs.
- Foreign exchange costs.
- Spread between buying and selling prices.
- Taxes where applicable.
A small annual fee may appear insignificant, but costs can compound over long periods because money spent on fees is no longer available for investment growth.
Tinywealth’s micro-investing fees guide looks specifically at costs beginners should check when using investment platforms.
12. Behavioural Risk
Not all investment risk comes from the investment itself.
Investor behaviour can also affect results.
For example, an investor may sell after a sharp market fall because they are worried about further losses, then buy back after prices have recovered. This can turn temporary market volatility into a realised loss and make it difficult to follow a long-term plan.
Other behavioural problems can include chasing investments that have recently performed well, trading too frequently, investing because of social-media excitement, or assuming that a recent trend will continue indefinitely.
A written plan, realistic expectations and an understanding of your own circumstances can help reduce the chance of making decisions based purely on short-term market movements.
13. Fraud and Scam Risk
Investors can also lose money because an opportunity is fraudulent rather than because the underlying market performed badly.
Warning signs can include promises of unusually high returns with little or no risk, pressure to invest quickly, unsolicited approaches, unclear ownership or regulation, and requests to send money through unusual channels.
The FCA maintains a register and warning information that investors can use when checking UK financial firms and possible scams.
Source: FCA consumer information.
If an investment opportunity is difficult to understand, independently verify the firm and the product before transferring money.
14. Regulatory and Platform Risk
The platform you use can introduce its own risks.
Before investing through an app or online platform, understand which company provides the service, whether it is regulated where relevant, how client assets are held, what happens if the platform fails, and what protections may or may not apply.
Protection arrangements are not the same as protection against investment losses. A compensation or safeguarding scheme, where applicable, does not normally mean that the value of your investments cannot fall.
Always check current rules and protections with the relevant regulator rather than relying on an old article or social-media post.
15. Tax Risk
Tax treatment can affect the return you ultimately keep.
Different investments and account types can have different tax treatment, and rules can change. Your own tax position may also depend on circumstances that are not covered by a general investing article.
For UK investors, use current information from HMRC and the FCA when making decisions about tax-sensitive investments.
Source: GOV.UK tax guidance.
How Different Risks Can Interact
Investment risks rarely appear one at a time.
Consider a hypothetical investor holding shares in a single overseas company. That investor could face:
- Company-specific business risk.
- Market risk.
- Concentration risk.
- Currency risk.
- Liquidity risk.
If the investor also needs the money in six months, time-horizon risk becomes important as well.
This is why simply asking “Is this investment risky?” is often too broad. A better question is: “What risks does this investment create for my particular goal?”
How Diversification Can Help
Diversification is one way investors can reduce exposure to individual investment or concentration risk.
For example, spreading investments across different companies, industries and regions can reduce the effect of a problem affecting one particular company or sector.
However, diversification has limits.
A diversified portfolio can still fall when the broader market declines. Diversification also does not eliminate inflation, currency movements, interest-rate changes or every other form of risk.
Tinywealth’s Asset Allocation vs Diversification article explains the difference between allocating money across asset classes and diversifying within and across them.
How Time Horizon Changes the Risk You Can Tolerate
The same investment can have different practical consequences for different goals.
Suppose two people each invest £10,000 in a diversified share portfolio.
Person A expects to need the money next year. Person B expects to use it in 25 years.
If the market falls sharply, both accounts can lose value. But Person A has a much shorter period before the money is needed. Person B may have more time for the portfolio to experience future market conditions.
This does not mean Person B is guaranteed to recover the loss, nor does it mean Person A should never invest. It illustrates why risk must be considered alongside the purpose and timing of the money.
A Beginner’s Risk Checklist
Before investing, ask:
- What exactly am I buying?
- How could I lose money?
- Could I lose part or all of the money?
- What could cause the investment to fall?
- How easy is it to sell?
- What fees will I pay?
- What tax rules could apply?
- Am I too concentrated in one company, sector or market?
- When will I need this money?
- Could I remain invested if the value fell significantly?
- Is the provider regulated where appropriate?
- Am I relying on a promise of guaranteed or unusually high returns?
What Beginners Should Avoid
“High return with no risk”
There is no general investment principle that allows high returns to be guaranteed without meaningful risk. Be especially cautious when an opportunity is presented that way.
Investing money you may need immediately
Money needed for essential short-term expenses has a different job from long-term investment capital.
Putting everything into one idea
A popular company, sector or investment theme can still perform badly. Popularity is not diversification.
Ignoring fees because the amount seems small
Repeated costs can have a larger effect over long periods than they appear to have at first.
Making decisions from past performance alone
Strong historical performance does not guarantee future returns.
How Micro-Investing Fits Into Investment Risk
Micro-investing can make investing accessible with smaller amounts of money, but smaller contributions do not automatically mean lower investment risk.
If a micro-investing account is invested in shares, the underlying shares can still rise and fall. If the account is concentrated in one company or narrow theme, concentration risk remains.
Fractional shares can allow investors to buy a portion of an investment, but fractional ownership changes the amount purchased rather than removing the risks of the underlying asset.
Tinywealth explains this in its fractional shares guide.
Risk and Reward: What the Phrase Really Means
You will often hear that investors need to take more risk to earn more return.
A more accurate way to think about this is that investments with uncertain outcomes may offer the potential for higher returns, but the outcome is not guaranteed. You can take substantial risk and still receive a poor return or lose money.
Risk should therefore be considered as something to understand and manage, not as a target to maximise.
The Bottom Line
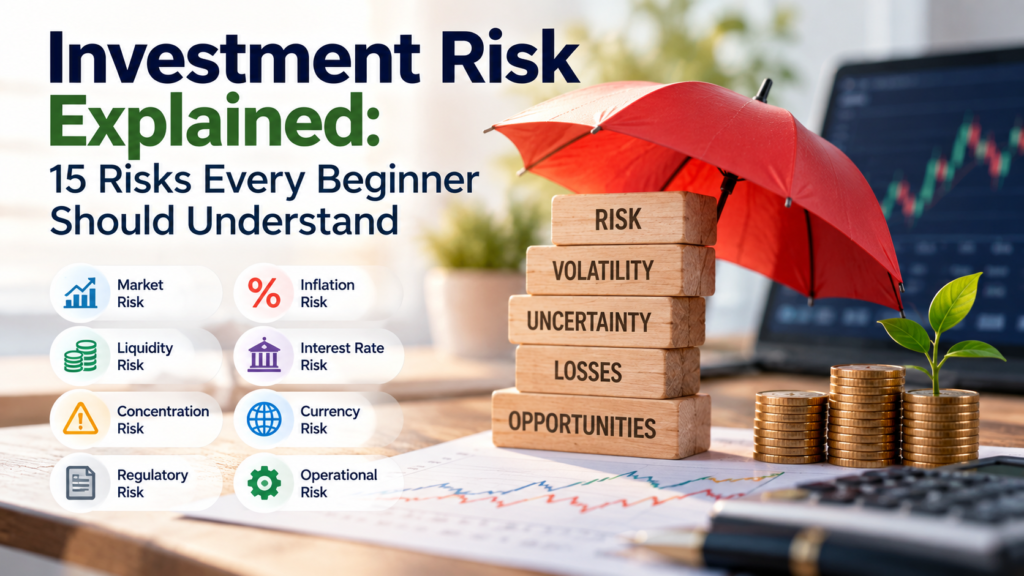
Investment risk is not one single thing. It includes market movements, company failures, concentration, inflation, interest rates, liquidity, currency changes, costs, taxes, fraud and investor behaviour, among other risks.
The right starting point for a beginner is not to search for an investment with “no risk.” Instead, understand what you are buying, identify the risks involved, consider when you will need the money, and decide whether you could cope with the possible outcomes.
Diversification can reduce some forms of concentration risk. A suitable time horizon can give you more flexibility around short-term volatility. Careful research can help you understand costs, providers and potential scams. None of these eliminates investment risk.
Educational note: This article is for general financial education and is not personalised investment, financial, tax or legal advice. Investments can fall as well as rise, and you may get back less than you invest. Check current information from relevant authoritative sources and consider regulated professional advice where appropriate.