
Quick answer: Diversifying a small investment portfolio means spreading your money across investments that do not all depend on the same company, sector, market or type of risk. You do not need a large portfolio to start thinking about diversification. The practical challenge for beginners is to build enough variety without collecting so many overlapping investments that the portfolio becomes difficult or expensive to manage.
For someone investing small amounts, diversification is especially useful because a single investment can have a large effect on the overall portfolio. But diversification is not a guarantee against losses. Markets can fall broadly, and a diversified portfolio can still lose value.
This guide explains how diversification works, how beginners can approach it with a smaller portfolio, common mistakes to avoid, and how diversification fits alongside regular investing and an emergency fund.
What Does Investment Diversification Mean?
Investment diversification is the practice of spreading money across different investments so that the portfolio is not dependent on one investment or one source of risk.
The basic idea is simple: if one holding performs poorly, the rest of the portfolio may reduce the impact. The Financial Conduct Authority describes diversification as spreading investments across different products and areas so you are less dependent on any one investment performing well. Investor.gov similarly explains diversification as spreading money among different investments to reduce overall risk.
Diversification can happen at more than one level:
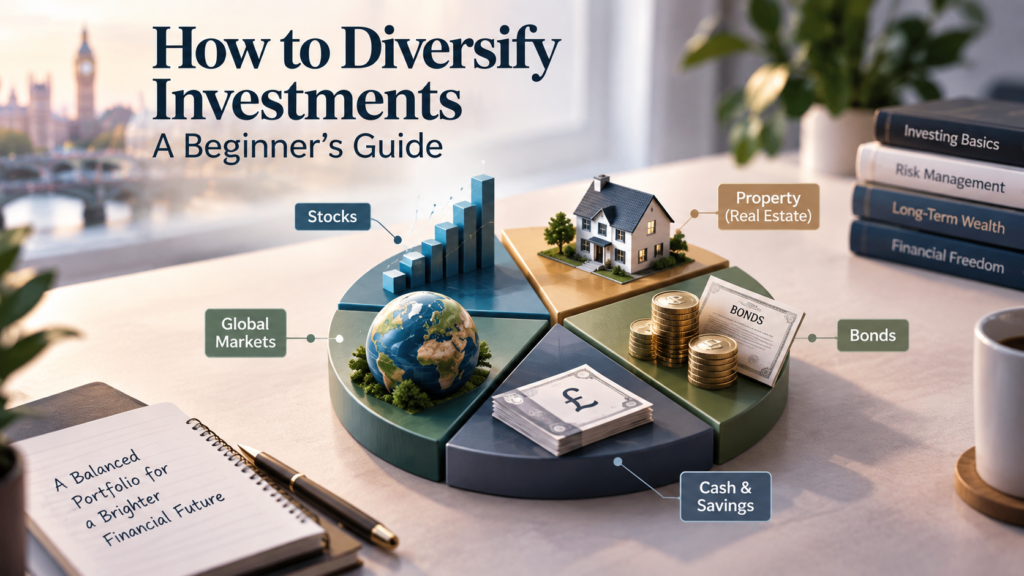
- Across asset classes: such as shares, bonds and cash.
- Across companies: rather than relying on one company.
- Across sectors: such as technology, healthcare, financial services and consumer businesses.
- Across markets and regions: rather than relying entirely on one economy or country.
- Within funds: by choosing funds or ETFs that provide exposure to a broad range of holdings rather than a narrow theme.
The aim is not to own everything. It is to avoid having one narrow exposure dominate the outcome of the whole portfolio.
Why Diversification Matters When You Invest Small Amounts
Small investors sometimes assume diversification is only relevant after a portfolio becomes large. In reality, the principle can be useful from the beginning.
Imagine a £300 portfolio invested entirely in one company. A major fall in that company’s share price can have a direct and significant effect on the whole portfolio. If the same £300 is spread across a broader collection of investments, the result of one company performing badly may have a smaller effect.
However, there is an important distinction between having several investments and being diversified. Owning five technology companies, for example, may still leave you heavily exposed to one sector. Likewise, owning several funds that all hold many of the same large companies may create the appearance of diversification without adding much additional exposure.
Investor.gov notes that diversification can reduce the impact of one investment performing badly, but it cannot guarantee that an investor will avoid losses when the wider market falls.
How to Diversify a Small Investment Portfolio
1. Start by identifying what you already own
Before adding another investment, list your current holdings and look at what they actually contain.
For each investment, ask:
- What asset class is it?
- Which companies or securities does it hold?
- Which sectors are represented?
- Which countries or regions are represented?
- How much of my total portfolio depends on this one exposure?
This step can reveal concentration that is not obvious from the name of a fund or platform.
2. Avoid building the portfolio around one company
Individual shares can be part of an investment strategy, but relying heavily on one company creates company-specific risk. A company’s earnings, management, competition, regulation, product demand or other events can affect its share price.
For a beginner, the important question is not whether a particular company is good or bad. It is whether the portfolio would become too dependent on that one company if it represented a large proportion of the total investment.
3. Look beyond a single sector
Sector concentration is another form of risk. If most of a portfolio is exposed to one industry, events affecting that industry can affect a large part of the portfolio at the same time.
Broad funds can sometimes make diversification easier because they can provide exposure to many companies and sectors through a single investment. But a fund is not automatically diversified. A narrowly focused sector fund can still be highly concentrated.
4. Consider geographic diversification
Investing across more than one market can reduce dependence on the economic conditions of a single country or region.
Geographic diversification does introduce additional considerations, including currency movements, different market structures, political and economic conditions, and potentially different costs. It should therefore be understood as another source of diversification rather than a reason to buy international investments simply for the sake of adding another country.
5. Understand the role of bonds and cash
Diversification does not mean that every portfolio needs a particular percentage of bonds or cash. The appropriate mix depends on factors such as the goal, time horizon and tolerance for investment risk.
Investor.gov explains that asset allocation involves dividing investments among asset classes such as stocks, bonds and cash, while the appropriate allocation depends on an investor’s circumstances. Tinywealth’s article on building an emergency fund before investing covers why money needed for unexpected expenses should be considered separately from money intended for long-term investment.
Can a Fund or ETF Give You Diversification?
Often, a fund or ETF can make diversification more practical for someone investing smaller amounts because one investment can provide exposure to many underlying securities.
But the label alone is not enough. Before investing, check what the fund actually holds.
| What to check | Why it matters |
|---|---|
| Number of holdings | A broader set of holdings can reduce reliance on a single company. |
| Top holdings | A fund can still be concentrated in a small number of large positions. |
| Sector exposure | Shows whether the fund is heavily dependent on one industry. |
| Geographic exposure | Shows whether the portfolio is concentrated in one country or region. |
| Fund objective | Helps you understand whether it tracks a broad market or a narrow theme. |
| Costs | Fees reduce the amount of money that remains invested. |
Investor.gov specifically cautions that a mutual fund or ETF is not necessarily diversified if it is narrowly focused. It also recommends checking underlying holdings when assessing diversification.
A Simple Example of Diversification
Suppose two beginners each have £500 to invest.
Portfolio A puts the entire amount into one company. The investor has one main source of company-specific risk.
Portfolio B uses a broader investment approach that gives exposure to many companies and possibly more than one asset class, depending on the investor’s objectives and circumstances.
If the single company in Portfolio A experiences a major decline, the effect on the portfolio can be substantial. In Portfolio B, a poor result from one holding may have a smaller effect because other holdings can behave differently.
This example does not mean Portfolio B cannot lose money. A broad market decline can affect many holdings at once. Diversification is about managing concentration risk, not eliminating investment risk.
How Regular Investing Fits Into Diversification
Regular investing and diversification solve different problems.
Regular investing describes how and when you contribute money. Diversification describes how your investments are spread across different exposures.
You can use both approaches together. Tinywealth’s guide to pound-cost averaging and regular investing explains how investing a fixed amount at regular intervals can change how purchases occur when prices move up and down.
Regular contributions can also gradually change the composition of a portfolio. If new money is directed toward an underrepresented area, the portfolio may become more balanced without requiring frequent buying and selling.
How Micro-Investing Can Support Diversification
Micro-investing can make it easier to begin with small amounts, but the same diversification principles still apply.
If a platform allows access to fractional shares or diversified funds, a smaller investor may be able to obtain exposure to a broader collection of investments without needing enough money to buy a whole share of every company.
That does not make every micro-investing product diversified. You still need to understand what you are buying, what it costs and what risks it carries.
For background, see Tinywealth’s guide to fractional shares and the Micro-Investing Guide.
Common Diversification Mistakes Beginners Make
Owning too many similar investments
Five funds may look diversified until you discover that they all hold many of the same companies. Compare their holdings instead of counting the number of investments.
Confusing more investments with lower risk
Adding investments does not automatically reduce risk. The relationship between the investments matters.
Ignoring fees
Costs can reduce the amount available for investment over time. Compare platform, fund and transaction costs where applicable rather than assuming that a diversified portfolio is automatically an efficient one.
Chasing recent winners
Buying an investment simply because it has recently performed well can increase concentration at exactly the wrong time. Diversification should be based on the role an investment plays in the portfolio, not only its recent performance.
Assuming diversification prevents losses
It does not. A diversified portfolio can still fall when markets or several asset classes decline together. The FCA and Investor.gov both emphasise that diversification can help manage risk but cannot remove investment risk.
When Should You Review Diversification?
There is no universal requirement to rebalance a portfolio on a particular schedule. Investor.gov explains that investments can drift away from an intended allocation as some holdings grow faster than others, and that investors may consider rebalancing based on their own plan.
For a small portfolio, unnecessary buying and selling can create costs and complexity. A useful review can begin with a simple question: Has the portfolio become meaningfully more concentrated than I intended?
When reviewing, look at the actual holdings rather than relying on the number of funds, apps or accounts you use.
A Beginner’s Diversification Checklist
- Know what you currently own.
- Check whether one company dominates the portfolio.
- Check for concentration in one sector.
- Review geographic exposure.
- Look through the underlying holdings of funds and ETFs.
- Consider whether different investments overlap.
- Understand the role of cash and other asset classes.
- Check the costs attached to your investments.
- Keep emergency savings separate from money intended for long-term investing.
- Review the portfolio when its risk or concentration changes materially.
The Bottom Line
For a beginner, diversification is less about owning a large number of investments and more about avoiding unnecessary concentration. A small portfolio can still be diversified if its exposures are thoughtfully spread across different companies, sectors, markets or asset classes.
Broad funds and ETFs can make diversification more accessible, but they still need to be checked for concentration and overlap. Regular investing can complement diversification by providing a disciplined way to add money over time, while an emergency fund helps keep short-term financial needs separate from long-term investment capital.
Most importantly, diversification should be treated as a risk-management principle rather than a promise of better returns. Investment values can fall, and diversification cannot guarantee that you will avoid losses.
Educational note: This article is for general financial education and is not personal investment, tax or financial advice. Your circumstances, goals, time horizon and tolerance for loss can affect what is appropriate for you. Consider researching investments carefully and, where appropriate, seeking regulated professional advice.