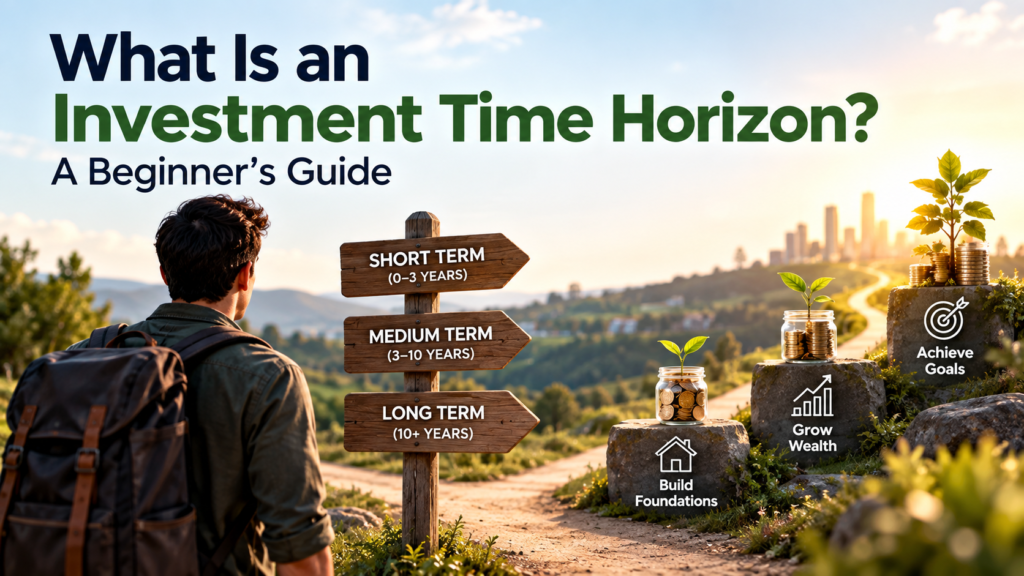

Quick answer: An investment time horizon is the length of time you expect your money to remain invested before you need to use it. It matters because the amount of time available can affect how much investment risk may be reasonable to consider, how much short-term volatility you may be able to tolerate, and whether an investment is suitable for the purpose of the money.
For a beginner, the important question is not simply “How long can I leave this money invested?” It is also “When might I need it, and what would happen if its value fell shortly before then?” A long time horizon does not remove investment risk, but it can give an investor more time to experience market cycles and recover from some temporary declines.
This guide explains what an investment time horizon means, why it matters, how short-, medium- and long-term goals differ, and how beginners can use the concept when thinking about savings and investing.
What Is an Investment Time Horizon?
Your investment time horizon is the period between investing money and the point when you expect to need to withdraw or use it.
For example, suppose you are saving for a house deposit that you expect to need in two years. Your time horizon for that particular goal is about two years. If you are investing money intended for retirement several decades from now, the time horizon for that goal may be much longer.
The same person can therefore have several investment time horizons at the same time.
| Goal | Possible time horizon | Key consideration |
|---|---|---|
| Unexpected expenses | Immediate / uncertain | Accessibility and stability are important |
| Planned purchase | Short term | A market fall close to the purchase date could be difficult |
| Medium-term financial goal | Several years | Balance growth potential with the possibility of needing the money |
| Retirement or long-term wealth building | Many years or decades | There may be more time to experience market cycles |
These are broad educational categories rather than fixed rules. A five-year goal can have very different characteristics depending on the person, the certainty of the deadline and the consequences of a loss.
Why Does Time Horizon Matter?
Investments do not move in a straight line. Shares, funds and other market-based investments can rise and fall, sometimes substantially.
If you need money soon, a large fall in market value can become more important because you may not have enough time to wait for a recovery. If the money is intended for a much later goal, short-term price movements may have less influence on the eventual outcome, although they still matter and losses are always possible.
The U.S. Securities and Exchange Commission’s Investor.gov explains that asset allocation decisions are influenced by factors including time horizon and risk tolerance. It also notes that investors with longer time horizons may be able to take on investments with greater volatility than investors with shorter horizons. This does not mean that a long horizon makes a risky investment safe.
Source: Investor.gov — Asset Allocation and Diversification.
Time Horizon Is Not the Same as Risk Tolerance
These two ideas are related, but they are not identical.
Time horizon asks: when will I need the money?
Risk tolerance asks: how much uncertainty or loss am I personally willing and able to accept?
Someone can have a long time horizon but still be uncomfortable with large fluctuations in investment value. Another person may be comfortable with market volatility but have a short deadline for a financial goal.
There is also a third consideration: risk capacity. This is about how much financial loss a person can actually absorb without seriously affecting their plans.
For example, a person saving for a major payment due next year may have high emotional tolerance for market volatility, but the short deadline can still make substantial investment risk inappropriate for that specific pool of money.
Short-Term Investing: When You May Need the Money Soon
Short-term money has a different job from long-term investment capital.
If you expect to need money within a relatively short period, the biggest issue may not be maximising investment growth. It may be preserving access to the money and reducing the possibility that a market decline leaves you with less than you need when the deadline arrives.
Examples can include:
- A house deposit you expect to use soon.
- A planned education payment.
- A major purchase with a known date.
- Money needed for a tax bill or other foreseeable obligation.
- Cash needed to cover an upcoming financial commitment.
That does not mean every short-term goal must use cash or that investing is automatically wrong. It means the consequences of a fall in value should be considered before exposing money to market risk.
For genuinely unexpected expenses, an accessible emergency fund can also play an important role. Tinywealth’s guide Should You Build an Emergency Fund Before Investing? explains why emergency savings and investments can serve different purposes.
Medium-Term Goals Need More Careful Thinking
Medium-term goals can be harder to classify because the time period may be long enough for investment growth to matter but short enough that a major market decline could still affect the plan.
Imagine someone expects to use £20,000 in five years. The question is not simply whether five years is “long enough” to invest. There is no universal answer that applies to every asset, investor or goal.
Instead, the investor can ask:
- Is the date fixed or flexible?
- What happens if the money is worth less when the goal arrives?
- Could the goal be delayed?
- How much of the required amount is already secured?
- Is the money needed all at once or gradually?
- What other savings or income could support the goal?
The more important and time-sensitive the goal, the more carefully short-term market risk needs to be considered.
Long-Term Investing and Market Volatility
Long-term investing is often discussed in connection with shares and diversified funds because investors may have more time to remain invested through periods of market volatility.
A long time horizon does not guarantee a positive return. Markets can fall, individual investments can fail, and a diversified portfolio can still lose value.
The benefit of time is that an investor may have more opportunity to continue contributing, experience different market conditions and allow long-term investment returns to compound. It can also reduce the importance of any single short-term market movement, depending on the goal and the investment.
This is one reason why money intended for retirement several decades away may be treated differently from money required for a purchase next year.
How Compounding Connects to Time Horizon
Compounding means that returns earned on an investment can themselves contribute to future returns when they remain invested.
Consider a simplified example. Suppose £1,000 earns an average return of 5% in a hypothetical scenario and all returns remain invested. After one year, the value would be £1,050 before costs and taxes. If the same hypothetical return continued, future growth would be calculated on the larger balance.
This example is only a mathematical illustration. Actual investment returns are not fixed, and real investments can lose value.
The important lesson is that time can give compounding more opportunity to operate. However, compounding works in both directions: losses and costs can also affect the amount available to compound.
Time Horizon and Regular Investing
Regular investing is another concept that should be kept separate from time horizon.
Regular investing describes how money is added to an investment. Time horizon describes when the money is expected to be needed.
For example, a person could invest £25 every month for a long-term goal. The monthly contribution is the investing method, while the number of years until the money is needed is the time horizon.
Regular contributions can also change the portfolio over time. New money may be directed toward investments that have become a smaller part of the overall portfolio, although the appropriate approach depends on the individual’s plan.
See Tinywealth’s Pound-Cost Averaging: How Regular Investing Works for Beginners for a deeper explanation of regular contributions and their limitations.
Time Horizon and Diversification
Time horizon does not replace diversification.
Diversification is about spreading investment exposure so that the outcome is not overly dependent on one company, sector, market or other source of risk.
A long-term investor can still have an overly concentrated portfolio. Likewise, a short-term saver can have a diversified set of investments but still face the problem that the whole market may fall near the date the money is required.
Tinywealth’s Asset Allocation vs Diversification guide explains how asset allocation and diversification answer different portfolio questions.
Time Horizon and Asset Allocation
Asset allocation is the way a portfolio is divided among broad asset classes such as shares, bonds and cash.
Investor.gov describes asset allocation as a decision influenced by time horizon and risk tolerance. The reasoning is straightforward: different asset classes have different characteristics, and the investor’s ability to tolerate short-term fluctuations can change depending on when the money will be needed.
There is no universal asset allocation that Tinywealth can recommend for every reader. A suitable structure depends on the goal, time horizon, risk tolerance, financial circumstances and other factors.
The useful principle is to connect the investment structure to the job the money is supposed to perform.
One Person Can Have Multiple Time Horizons
This is one of the most useful ideas for beginners.
Suppose someone has:
- £2,000 reserved for unexpected expenses.
- £8,000 intended for a home-related expense in three years.
- £15,000 intended for a long-term investment goal 20 years away.
It would be misleading to say that this person has “a” time horizon. Each pool of money has a different purpose and therefore a different time horizon.
The emergency money needs accessibility. The three-year goal has a defined future need. The 20-year money may have more time to experience market cycles.
Thinking in separate “buckets” can therefore be more useful than looking at a single overall savings or investment balance.
What Happens When Your Time Horizon Changes?
A financial plan should not be treated as permanent.
Your time horizon can become shorter as a goal approaches. A person saving for retirement at age 30 has a different horizon from the same person at age 60.
Other changes can also matter. You may decide to buy a home earlier, change your retirement date, start a business, return to education or face a new financial obligation.
When the expected use of the money changes, it can be sensible to review whether the investment structure still matches the goal.
Market movements can also change the portfolio’s proportions. That is why portfolio reviews can involve both the original goal and the current holdings.
A Simple Investment Time Horizon Framework
Instead of trying to memorise an exact number of years for every category, beginners can work through a sequence of questions.
- What is the money for? Give the goal a name.
- When might I need it? Identify the expected date or range.
- How flexible is that date? A flexible goal is different from a fixed obligation.
- What happens if the investment falls? Consider the practical consequences rather than only the percentage loss.
- How much can I afford to lose? Consider financial capacity as well as emotional comfort.
- What other resources do I have? Savings, income and other assets can affect the plan.
- Does the investment match the purpose? Check risk, access, costs and diversification.
This framework does not produce a personalised investment recommendation. It simply helps separate the questions that need to be considered.
Common Time Horizon Mistakes
1. Treating “long term” as a guarantee
A long horizon does not guarantee that an investment will rise. It only gives the investor more time before the money is required.
2. Ignoring the date the money is actually needed
Someone may describe an investment as long term while planning to withdraw it in two years. The actual purpose and expected withdrawal date are more useful than the label.
3. Using the same strategy for every goal
Emergency savings, a future purchase and retirement wealth can have completely different requirements. Combining them into one investment decision can hide important differences.
4. Forgetting about liquidity
An investment can be appropriate for a long-term goal but inconvenient to access for an immediate expense. Check how and when money can be withdrawn before committing funds.
5. Overlooking costs and taxes
Investment returns are not the only factor affecting outcomes. Platform charges, fund fees, dealing costs and applicable taxes can reduce what remains available. Current rules should be checked with authoritative sources because they can change.
Investment Time Horizon vs Holding Period
These terms can sound similar but are not necessarily identical.
Your time horizon is connected to when you expect to need the money. Your holding period describes how long you actually hold a particular investment.
You may intend to invest for 20 years but sell one investment after five years because it no longer fits your plan. Conversely, you may hold an investment longer than expected because your goal has changed.
The two concepts can overlap, but they should not be treated as interchangeable.
What About Inflation?
Time horizon also matters because prices can rise over time.
If you keep money for many years, the amount of goods and services that the same number of pounds can buy may change. This is commonly described as inflation reducing purchasing power.
That creates a trade-off for long-term financial planning. Cash can offer stability and accessibility, while long-term investments may provide the potential for growth but introduce market risk.
Neither option is automatically correct for every goal. The relevant question is what role the money has and what risks are acceptable for that purpose.
How Time Horizon Fits Into a Beginner Investing Plan
A simple learning sequence can help:
- Put day-to-day finances in order.
- Consider accessible emergency savings for unexpected costs.
- Identify the specific goals you are saving or investing for.
- Give each goal an expected time horizon.
- Understand the investment risks and costs involved.
- Learn about diversification and asset allocation.
- Review the plan when your goals or circumstances change.
The FCA’s InvestSmart resources also emphasise understanding risk, keeping your finances in order and considering whether an investment is suitable for your circumstances before investing.
Source: FCA InvestSmart.
Questions to Ask Before Investing for a Goal
- When is the money likely to be needed?
- Is the date fixed or flexible?
- Could I cope if the investment temporarily lost a significant amount?
- Would a loss force me to change the goal?
- Can I access the money when I need it?
- What fees apply?
- What tax rules could affect the outcome?
- Is the portfolio diversified?
- Do I understand what I actually own?
- What would make me review the plan?
The Bottom Line
An investment time horizon is simply the period between putting money to work and expecting to need it. Despite being a simple idea, it can influence many other investing decisions.
Short-term money may need a greater focus on accessibility and protection from a poorly timed market fall. Longer-term money may have more time to experience market cycles and benefit from compounding, but it still carries investment risk.
The most important lesson is that time horizon belongs to the goal, not just to the investment account. One person can have several different time horizons because different amounts of money can have different jobs.
Understanding the time horizon first can make it easier to think about risk, diversification, asset allocation, liquidity and costs. It does not tell you exactly what to buy, but it gives you a clearer framework for evaluating whether an investment approach matches the purpose of your money.
Educational note: This article provides general financial education and is not personalised financial, investment, tax or legal advice. Investment values can fall as well as rise, and you may get back less than you invest. Before making a financial decision, consider your own circumstances and check current information from relevant authoritative sources or seek regulated professional advice where appropriate.